A checkout under the institution's brand, hosted or embedded
The institution's checkout, hosted on its own domain or embedded in the merchant's app, taking cards, DuitNow QR, FPX and the major Malaysian e-wallets.
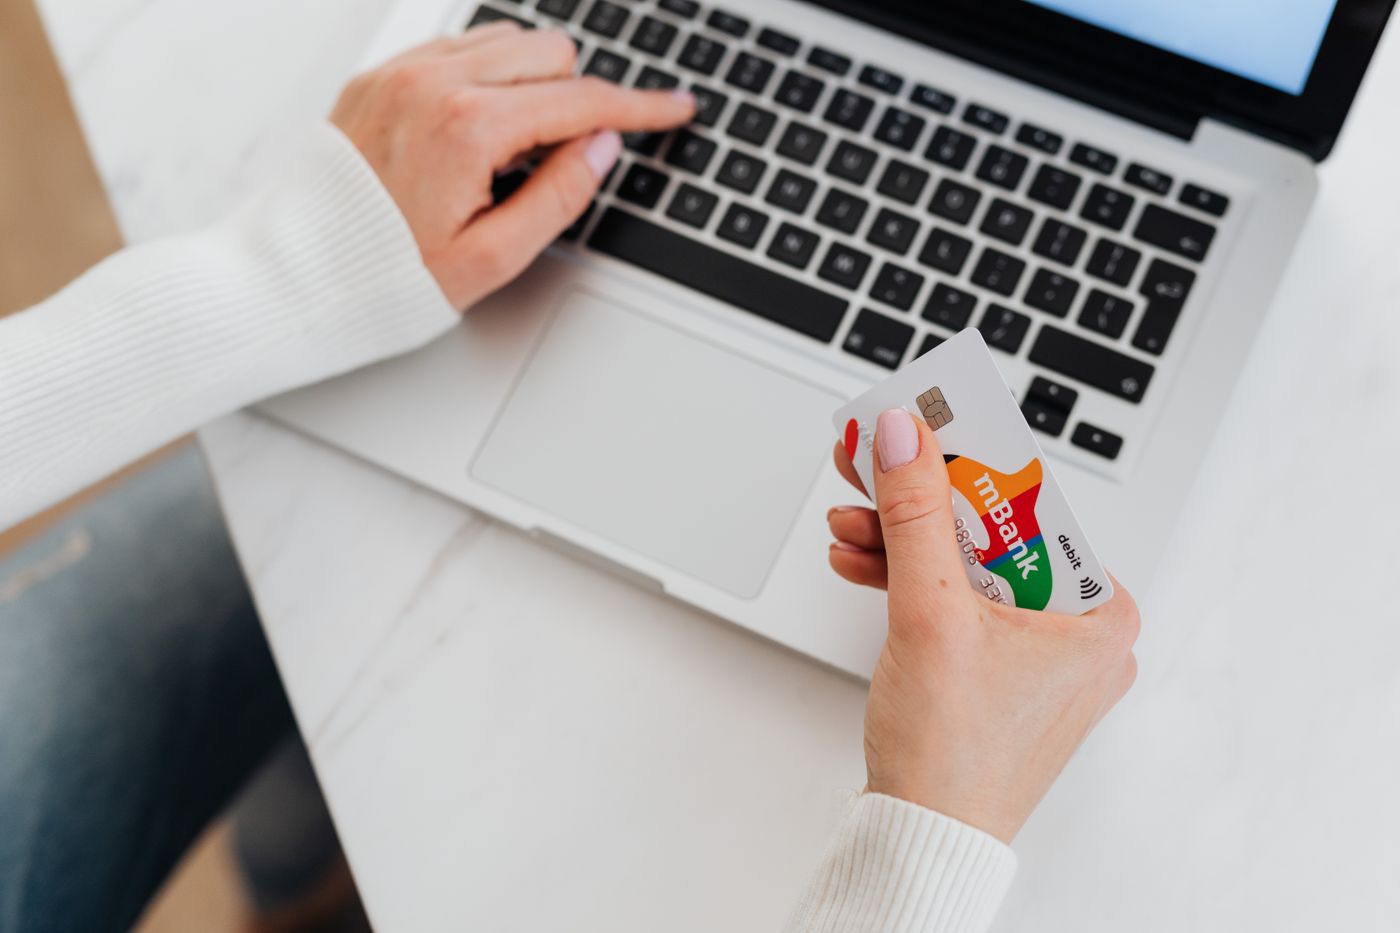
The hosted checkout
The institution's page on its own domain, with the merchant's logo on top and the order beside it. The customer chooses how to pay, and the store never sees the card or the bank login.
- Cards, DuitNow QR, FPX and e-wallets
- A default method order the institution sets
- English and Bahasa Malaysia
Each method, in plain words
3-D Secure shows as a confirmation in the customer's own bank app, with a timer and a way out. DuitNow QR is a code for one order that expires, with a button to open the bank app on the same phone.
- FPX by bank, with a slow bank announced and DuitNow QR offered
- E-wallets as one method, with the wallet chosen inside it
- A decline that says what happened and what to do next
The embedded checkout
The same methods and rules inside the merchant's own app or page, through SDKs for web, iOS and Android. The card fields are the processor's, rendered inside the SDK, so the app never handles a card number.
Receipts and e-invoices
One receipt format for every method and product, sent by email or SMS in the merchant's brand. The customer can ask for a MyInvois e-invoice from the paid screen or the receipt, and MyInvois validates the TIN before the receipt is sent.
- Consolidated B2C e-invoices submitted for each merchant on the institution's schedule
- A refund receipt with the original reference
Measured at every step
Sessions, completion and abandonment are measured at each step, so a slow bank page is not blamed on the merchant.
See it with your own merchants
Send us the methods you take, the number of merchants and the payment and account systems in place. An engineer replies with a rollout plan, a list of decisions to agree and a proposal.